COP31 Turkiye Forecast Strategic Agenda Sustainable Development Global Affairs: Key Issues

adminsustainabilityrepositorygroup@gmail.comEdit Profile

COP31 Turkiye forecast strategic agenda Sustainable Development global affairs

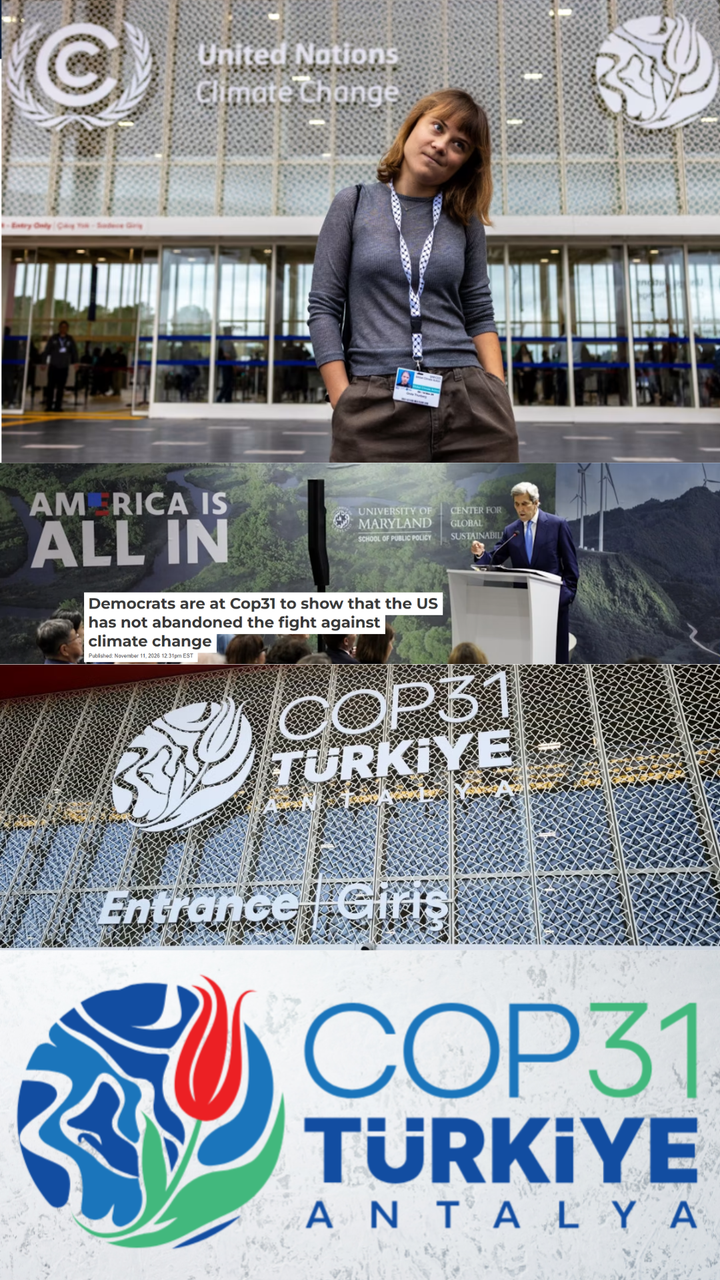
COP31 is a test of whether countries can turn climate commitments into funded action without ignoring development needs, economic pressures or vulnerable communities. In Antalya, the central question is whether international cooperation can make policy practical without treating development as a single, settled priority. A city preparing for a climate conference offers a familiar scene: visitors arrive, local businesses adjust, and the global debate meets daily life. The stakes reach far beyond the venue. Finance, energy, community resilience, technology and trade will shape whether the summit’s plans can work in practice. This COP31 forecast gives global professionals, travelers, cultural diplomats and conscious consumers a clear way to assess the choices ahead. The summit’s real measure will be whether cooperation produces projects and policy changes that can be tracked beyond the conference.
How do Türkiye and Australia divide COP31’s roles?

Türkiye hosts COP31 in Antalya, while Australia’s Chris Bowen leads negotiations and Murat Kurum is nominated as conference President. Their roles differ: Türkiye hosts and steers the Presidency, while Australia leads formal negotiating work.

The United Nations Framework Convention on Climate Change (UNFCCC) is the treaty framework for international climate talks. COP31 is its thirty-first Conference of the Parties, alongside the twenty-first meeting under the Kyoto Protocol and the eighth under the Paris Agreement. The conference runs from 9 to 20 November 2026 in Antalya.

Türkiye and Australia work in close partnership under the Türkiye-Australia Partnership Modalities. That arrangement supports shared planning; it does not transfer one country’s authority to the other. The Paris Agreement entered into force on 4 November 2016, so COP31 falls in its tenth anniversary year. An anniversary can mark time, though it cannot certify progress.

UNFCCC’s COP31 preparations describe the partnership and the Antalya dates. The institutional calendar also includes meetings linked to two earlier climate agreements, each with its own rules and history.

Türkiye hosts and leads the conference Presidency; Australia leads negotiations through a partnership, not a transfer of authority.

For delegates, the division matters because hosting, agenda-setting and negotiating are related but distinct tasks. The Presidency helps guide the process and convene parties, while negotiators seek agreement on the formal text. Keeping those roles clear helps readers interpret announcements and disagreements. The split places diplomatic coordination and formal negotiating work in two national hands, making partnership essential to the conference’s process.

What Does the COP31 Turkiye Forecast Strategic Agenda Sustainable Development Global Affairs Mean for Delivery?

Delegates in business attire sit around an oval conference table covered with maps and documents, discussing climate commitments and implementation measures. A screen displays climate graphs and statistics beside a digital clock in a modern conference room with large windows.

COP31’s implementation test is whether countries can show progress on existing commitments while negotiating over who pays and how results are measured. Delivery means evidence, not just new language: plans need funds, owners and progress checks.

The Global Stocktake is the UNFCCC’s five-year process for assessing collective progress under the Paris Agreement. Its second round begins at COP31. The stocktake matters because national climate plans and real-world action can diverge. An inventory can reveal where commitments stand, even when it cannot make countries meet them.

The formal negotiating agenda is not the same as the Presidency’s complementary Action Agenda. On 9 November 2026, Türkiye and Australia adopted the agenda after parties sought to add climate-related unilateral trade measures and a proposal to triple adaptation finance. Both issues were left off. Consensus can keep talks moving, but exclusions show where agreement remains difficult.

The formal process must test delivery on three practical points:

  • Whether commitments have a reliable source of financing.
  • Whether delivery plans name accountable institutions and clear steps.
  • Whether progress can be measured and reported over time.

These checks help distinguish a climate action pledge from a funded programme. They also make policy easier to compare across countries, though national conditions differ. The Paris Agreement sets a shared direction, while each country chooses its own NDCs and measures. Strong implementation depends on climate plans that can be examined, not simply announced.

That distinction matters for international cooperation. Countries may agree on the need to act while disputing the costs, rules or measures used to judge success. The agenda’s omissions make clear that a focus on delivery does not remove disagreement over the rules of delivery.
Electricity and trade pressures meet at the industrial transition

The COP31 electrification target makes electricity demand a strategic issue, while carbon rules increasingly influence where high-emissions industries can compete. Power supply matters because factories, transport and buildings cannot switch energy sources by declaration alone.

On 9 June 2026, the incoming Presidency set a target to raise electricity’s share of final energy demand from just over 20% to 35% by 2035. Electrification is not the same as phasing out fossil fuels. The climate gains depend on how electricity is generated and whether grids can meet added demand.

Electrification puts power demand at the center

A larger electric share can shift energy use away from direct fuel burning. It can also raise demand for reliable power, new grid links and storage. The target is a direction for climate action, not proof that clean electricity will reach every user.

Investors will watch whether power systems can support industrial change at a workable cost. A factory that replaces a fuel-fired process still needs a stable supply. The energy transition can falter when new demand arrives before infrastructure.

Carbon border rules reshape regional trade

The EU’s Carbon Border Adjustment Mechanism (CBAM) applies a carbon cost to some imports. It can change trade incentives, but its effects will vary by product, company and market conditions.

In the third quarter of 2026, Western Balkan electricity exports to the EU fell 17% year on year as CBAM costs exceeded coal-fired power’s price advantage. That change shows a price signal, not a guarantee of industrial transformation. Carbon rules may shift costs across borders without funding cleaner plants or protecting every producer.

China was projected to face more than €1.3 billion in annual EU CBAM fees at full ramp-up. Low-carbon technology could bring net financial benefits for Chinese steel producers. The contrast shows why the same rule can create costs for some firms and an incentive for others.

Steel decarbonization tests the investment case

Türkiye’s steel sector would need around €30 billion over the next two decades. Carbon pricing could generate up to €1.5 billion annually for decarbonization, a potential contribution rather than a complete financing plan.

On 9 November 2026, the EU and UK agreed draft carbon-market linkage provisions. They cover emissions caps, allowance-supply controls and a British Market Stability Reserve. The draft points to closer market rules, but does not settle every trade effect.
Place or marketQuantified signalTime or conditionTransition implication
TürkiyeUp to €1.5 billion yearly; about €30 billion neededRevenue potential; next two decadesPricing could help, but leaves a large investment need
ChinaMore than €1.3 billion yearly in EU feesAt full CBAM ramp-upLow-carbon steel could improve net returns
Western BalkansElectricity exports fell 17%Third quarter of 2026, year on yearCBAM costs outweighed coal power’s price edge

For investors and policymakers, the key check is whether clean power, industrial upgrades and trade rules advance together rather than pulling in different directions.

Can climate finance reach adaptation needs?

A woman in a blazer and a man in a suit point to a local map on a table as they discuss adaptation projects. Behind them, community members plant crops near solar panels and wind turbines, with hills in the distance.

The adaptation-finance challenge is not only the size of the gap, but also the lack of agreed rules for measuring whether support arrives. Clear rules matter because a pledge without a baseline or delivery plan is hard to assess.

The COP30 agreement to triple adaptation finance by 2035 still had no agreed exact target, baseline year, delivery roadmap or accountability roadmap by COP31. Without these details, countries cannot easily judge whether the promise is on track. Adaptation finance supports measures that help people and systems cope with climate impacts.

Adaptation commitments still need delivery rules

International public adaptation finance to developing countries was estimated at approximately $26 billion annually. Projected annual needs by 2035 range from $310 billion to $365 billion. The figures describe different sides of a large financing challenge.

Finance measureAmountTime or scope
International public adaptation financeApproximately $26 billion yearlyDeveloping countries
Projected adaptation needs, low end$310 billion yearlyBy 2035
Projected adaptation needs, high end$365 billion yearlyBy 2035

A baseline helps show what counts as new support. A delivery plan explains when funds should arrive and how they will reach countries. Accountability measures make it possible to compare promises with results, rather than treating every announcement as a completed transfer.

Loss and damage demand exceeds start-up funding

Adaptation finance is distinct from funding for loss and damage. Adaptation seeks to reduce harm before or as impacts occur; loss and damage support responds to climate-related harm that cannot be avoided or fully adapted to.

By June 2026, the Fund for Responding to Loss and Damage had received 176 requests from 119 countries, totalling $2.8 billion. Its start-up phase had a total allocation of $342 million. Requests and allocated start-up funds measure different things. The request total reflects demand; the allocation describes the fund’s initial resources.

Finance access is part of the justice question

Countries with limited fiscal space may struggle to borrow for recovery or resilience without increasing debt pressure. Access rules can shape whether support reaches places facing high risk, not only those with strong project teams.

Finance must also arrive in a form countries can use. Grants, loans and other support carry different costs for public budgets. A credible finance pathway needs clear amounts, predictable delivery and a way to track who receives support.

Turning national commitments into investable projects

An NDC becomes investable only when a national priority is translated into a defined project that finance institutions can assess. Project detail is the hinge between a climate promise and a decision to commit capital.

By mid-2026, 147 Parties had submitted updated Nationally Determined Contributions (NDCs), the national climate plans under the Paris Agreement. The Climate Implementation Bridge is intended to help turn those plans into investable project portfolios and help climate finance reach the ground faster. It supports project preparation and coordination; it is not a new source of money.

A practical project pipeline can follow four stages:

  1. Identify a national priority linked to climate and development needs.
  2. Prepare a project with clear costs, aims and delivery steps.
  3. Coordinate public and private finance around the project.
  4. Track delivery and report progress against agreed measures.

These steps require public agencies, lenders and private investors to work from a shared project plan. If costs, ownership or expected results remain vague, finance teams cannot judge risk with confidence. The bridge is meant to shorten that distance, not remove the need for sound project design.

Several scheduled meetings show how finance work can cross institutional lines. On 13 November 2026, Türkiye’s Treasury and Finance Minister Mehmet Şimşek and the Presidency are scheduled to host a ministerial meeting on cross-government action for economic transformation.

The Asian Development Bank and the Coalition of Finance Ministers for Climate Action are scheduled to introduce a proposed Fiscal Resilience Platform for Central and West Asia. The event is set for the Tajikistan Pavilion from 14:00 to 15:00.

The UK Pavilion is scheduled to host a 13 November event on scaling transition finance through investor frameworks and sector planning. These sessions connect finance policy, regional planning and investment practice. Investors should test whether a proposed portfolio has project detail, institutional ownership and a credible route to implementation.

Action Agenda targets connect waste, buildings, farms and health

Professionals in business attire review digital screens with waste and renewable energy metrics. Behind them, green-roofed buildings with solar panels and vertical gardens line a river, with wind turbines in the distance.

COP31’s Action Agenda makes resource efficiency tangible through separate targets for waste growth, building energy intensity and circular materials. Separate measures matter: a waste-growth limit is not a promise to halve all waste.

The agenda aims to halve the growth in global waste by 2035. It also seeks lower energy use in buildings and greater use of circular materials. These are distinct goals, each with its own measure and route to action.

Waste and circular materials put resource use on the scorecard

Halving projected growth means slowing the increase in waste, not cutting total waste in half. The Action Agenda also targets a global circular material use rate of at least 15%. Reuse and recycling can help keep materials in use, though the measure is not the same as total waste generation.

Türkiye generates approximately 36 million tons of solid waste annually. Its Zero Waste Project has a recovery-rate goal of 35%. Those national figures differ from the global COP31 targets: one tracks waste generated and recovered in Türkiye, while the other sets global aims for waste growth and material use.
Building efficiency links cities to lower energy demand

The agenda targets at least a 25% reduction in building-sector energy consumption intensity by 2035. The measure focuses on energy used relative to a building-sector baseline, rather than a simple count of buildings or city size.

Cities can make the target real through building upgrades, better design and lower energy demand. Progress will depend on choices by owners, builders and local authorities. A global percentage cannot repair a drafty home by itself, although it can help set a common direction.

Agriculture and health broaden resilience

The Action Agenda aims to train all young farmers in climate-resilient agricultural practices. Training can help farmers plan for changing conditions and protect livelihoods, while local needs shape which methods prove useful.

The Food, Agriculture and Health thematic day is scheduled for 9 November 2026. The Antalya Initiative for Health Resilience is also scheduled to launch that day. Their pairing reflects how climate change can affect food systems and health together.
Action areaTarget or initiativeDeadline or date
WasteHalve growth in global wasteBy 2035
BuildingsCut energy consumption intensity by at least 25%By 2035
Circular material useReach at least 15%Global target
Young farmersTrain all young farmers in climate-resilient practicesAction Agenda target

The targets will matter most when cities, farmers and institutions can translate them into local practice and report results.

Indigenous and local knowledge must reach policy

Indigenous and local knowledge has a route into UN climate work through the Local Communities and Indigenous Peoples Platform (LCIPP), although observer participation is not the same as a Party’s decision-making authority. Access matters, but the formal roles remain distinct.

The LCIPP was established in 2015 to strengthen knowledge and engagement in climate policy. Its Facilitative Working Group has equal representation between Indigenous Peoples and Parties. Indigenous Peoples take part under the UNFCCC as observers, not decision-making Parties.
The platform creates routes for knowledge and engagement

The platform has three functions:

  • Support knowledge exchange among Indigenous Peoples, local communities and other participants.
  • Build capacity for engagement in climate processes.
  • Bring diverse ways of knowing into climate policies and actions.

The International Indigenous Peoples’ Forum on Climate Change organizes the Indigenous constituency in the UNFCCC process. The equal make-up of the Facilitative Working Group gives Indigenous Peoples and Parties equal representation in that body. It does not give Indigenous observers the same formal vote as Parties.

COP31 gatherings bring knowledge holders into the process

The Annual Gathering of Knowledge Holders is scheduled for 9-10 November 2026. The Seventh-Generation Round Table is scheduled for 10 November, from 15:00 to 18:00 UTC+03.

The Annual Dialogue is scheduled for 12 November, from 13:00 to 15:00 UTC+03. These gatherings offer routes for sharing knowledge and engaging with climate work. Participation and formal authority are not interchangeable.

That distinction matters when assessing how policy reflects community knowledge. An invitation can create space for input, but the decision structure determines who can shape negotiated outcomes. Readers can assess inclusion by checking both who is invited to contribute and who holds formal authority in the process.

AI tools bring climate risk down to district level

Aerial view of a modern city divided into districts, with colorful climate-risk maps and charts layered over satellite imagery. Professionals examine tablets showing data, while homes, green spaces, warning symbols, skyscrapers, and high-tech infrastructure fill the scene.

CLIMAID illustrates how AI can combine satellite and household data to map climate risks at district level. Its value is practical: the platform is designed to help local teams see risks that broad national maps can miss.

The COP31 Presidency’s 2026 AI for Climate Action Award went to CLIMAID, an open-source platform. It combines artificial intelligence, satellite observations, geospatial information and household vulnerability assessments. That mix supports district-level planning, not automatic protection from climate impacts.

CLIMAID supports district-level risk mapping, drought prediction and early warning. It can also support adaptation planning and assessments of climate-related loss and damage. These uses connect climate data to decisions about where preparation or response may be needed.

The award was organized by the UN Climate Change Technology Executive Committee, the Climate Technology Centre and Network, KOICA and the Royal Government of Cambodia. Their role shows that climate technology work can involve several institutions, not just software developers.

AI can sort data and flag patterns, but its outputs depend on the quality and reach of the data. Household vulnerability assessments may add local detail, while satellite observations can show changes over wide areas. Neither replaces the judgment of people who know a district’s conditions.

A warning also helps only if local institutions can respond. They need clear roles, plans and ways to reach residents before hazards grow. Any digital risk tool still needs reliable data, local knowledge and institutions able to act on its warnings.
Regional partnerships shape the summit’s diplomatic leverage

Türkiye’s diplomatic leverage will depend on whether regional partnerships can connect climate goals to the development and economic priorities of different countries. That bridge is possible, but geography alone does not build trust or shared policy.

Türkiye ratified the Paris Agreement in 2021 and adopted a climate-neutrality goal for 2053. It sits near Europe, the Middle East, Central Asia and Africa, which may give it room to connect discussions across regions. That role depends on cooperation that produces shared action, not location alone.

Germany and Türkiye have jointly chaired the Climate Club since 2026; the club was established in 2022. Their cooperation offers a channel for discussion on industrial transition and climate policy. It does not mean that all members share identical economic needs.

The EU and Türkiye have common interests in industrial decarbonization, sustainable finance and modernizing value chains. Those interests can support cooperation on investment and production. The hard work lies in aligning rules and benefits across firms and communities.

The tension between international development and global development is best read as a debate over priorities. Who sets them, who pays, and how local needs shape global policy are open questions, not fixed camps. Countries may support shared climate goals while disagreeing on the route and cost.

Türkiye could help connect those views across regions, while also pursuing its own economic aims. A bridge-building claim is strongest when it produces cooperation that can be seen in shared policy or investment.

Key dates turn the agenda into a working programme

Delegates in business attire review a colorful calendar of COP31 themed climate days in a conference hall decorated with greenery. Nearby groups discuss sustainable development, with a Turkish city skyline visible through large windows and The Sustainable Digest branding in the decor.

COP31’s programme moves from food, agriculture and health on 9 November to final negotiations on 20 November, with themed days in between. The dates matter because each theme gives practitioners a focused point of entry.

The Leaders’ Summit is scheduled for 11-12 November 2026. The resumed High-Level Segment for heads of state and government is scheduled for 17-18 November. Final negotiations are scheduled for 20 November.

Five anchor moments can help delegates and remote observers plan their attention:

  • 11-12 November: Leaders’ Summit.
  • 13 November: Finance and Trade thematic day.
  • 16 November: Science, Industry and Technology thematic day.
  • 17-18 November: Resumed High-Level Segment.
  • 20 November: Final negotiations.

The programme opens with Food, Agriculture and Health on 9 November. The other themed days are Energy and Transport on 10 November, Zero Waste on 11 November, and Resilient Cities and Built Environment on 12 November.

Finance and Trade follows on 13 November, then Children, Youth, Education and Skills on 14 November. Science, Industry and Technology is set for 16 November. Ocean, Seas, Nature and Land Use follows on 17 November.

Human and Social Development is scheduled for 18 November, while 19 November is İmece: Enhancing Implementation. These themes give policymakers, researchers, civil society and practitioners different ways into the wider process. The schedule does not ensure that a theme will produce agreement, but it can help people find the relevant discussion.

A themed day offers a useful route into the programme, but the date alone cannot show whether negotiations will produce agreement.

Remote followers should use the date and theme together to identify the sessions most relevant to their work.
Conclusion

COP31’s strategic value will rest less on declarations than on whether commitments produce visible changes in policy, finance and resilience. Follow-through is the test, and it depends on clear accountability and meaningful participation as well as money.

Professionals and observers can track whether national commitments lead to funded projects and measurable progress. The practical next step is to compare announced commitments with the projects, budgets and progress reports that follow Antalya.

Key Takeaways

  • Antalya hosts COP31 from 9 to 20 November 2026.
  • Türkiye hosts the summit, while Australia leads formal negotiations.
  • Delivery depends on finance, clear plans and measurable progress.
  • Energy and trade policy can shift costs across borders.
  • Local knowledge and reliable data matter for effective climate action.
  • Follow-through after the summit will matter more than declarations alone.

2026 SDSN Sustainable Development Report annual review analysis

2026 SDSN Sustainable Development Report annual update review analysis

The latest edition of the 2026 SDSN Sustainable Development Report marks a significant moment in global efforts toward a more equitable future. It reflects a decade of data and progress since the adoption of the 2030 Agenda by all UN Member States. This document serves as a crucial tool for understanding the trajectory of development across nations.

In this year’s report, the SDSN Sustainable Development Solutions Network has identified eight key priorities aimed at accelerating progress through 2030 and beyond. This strategic shift emphasizes the importance of looking forward, rather than solely reflecting on past achievements.

Moreover, the report features insights from two innovative surveys that gauge both expert opinions and public perceptions regarding the barriers to implementing these vital goals. As nations navigate complex challenges, the findings serve as a guide for policymakers and stakeholders alike.

As we delve into the details, it becomes clear that the rankings of countries such as Finland, Sweden, and Denmark are not just a celebration of their achievements. They represent a commitment to long-term strategies that foster positive impacts both domestically and internationally.

1. Introduction to the SDSN and UN DESA Roles in Sustainable Development

At the forefront of global initiatives, the Sustainable Development Solutions Network and the United Nations Department of Economic and Social Affairs collaborate to advance significant goals. Their combined efforts have shaped the landscape of international development, particularly since the adoption of the 2030 Agenda in 2015.

1.1 Historical Background of the Sustainable Development Solutions Network

The Sustainable Development Solutions Network emerged as a brain trust under UN auspices. Since 2015, it has mobilized global academic and research expertise to tackle the most intractable challenges facing all 193 member states. This initiative emphasizes collaborative approaches to sustainable development.

1.2 Overview of the United Nations Department of Economic and Social Affairs

UN DESA’s long-term history as the Secretariat’s economic social arm stretches back decades. However, its role crystallized dramatically after 2015, when it became the backbone for the High-Level Political Forum. This forum serves as the custodian of the Voluntary National Review process across 193 member states.

1.3 Synergies between SDSN and UN DESA in Global SDG Efforts

The synergy between SDSN and UN DESA is evident in their complementary data collection efforts. SDSN leverages its global network of academics to track the evolving landscape of sustainable development. Meanwhile, UN DESA maintains the official SDG indicator framework that informs monitoring processes.

Since 2016, both organizations have strengthened governance systems through bilateral relationships with national and regional governments. This collaboration is crucial for effective implementation of the sustainable development goals.

OrganizationRoleKey Contributions
Sustainable Development Solutions NetworkMobilizes research expertiseAddresses complex challenges in 193 member states
United Nations Department of Economic and Social AffairsServes as the Secretariat’s economic social armCustodian of Voluntary National Review process
CollaborationData collection and governanceStrengthens systems for sustainable development

Short-term progressions have seen both institutions grappling with the declining emphasis on sustainable development in high-level discussions. This trend underscores the urgency of their collaborative efforts in fostering a sustainable future.

2. Evolution and Annual Development of the 2026 SDSN Sustainable Development Report

A dramatic visualization of the evolution of the Sustainable Development Report, featuring a timeline that showcases key milestones with symbolic icons—like renewable energy, education, and community growth—interwoven through a vibrant landscape. In the foreground, diverse professionals in business attire discuss and analyze reports, radiating a sense of collaboration. The middle ground is filled with visuals representing data visualization elements, such as graphs and charts, seamlessly merging with lush greenery and cityscapes, symbolizing progress. In the background, a warm golden sunset casts dramatic lighting, creating an optimistic atmosphere. The overall mood is one of hope and collective advancement toward sustainability. The image embodies the essence of "The Sustainable Digest" and reflects the themes of evolution and development.

The evolution of these reports mirrors the dynamic nature of global development efforts and the pressing need for accountability. Since 2015, the series has transformed from a basic scorecard into a comprehensive tool for assessing progress across nations.

2.1 The Report’s Genesis and Long-Term Development Since 2015

The sustainable development report series began its journey in 2015. It aimed to hold all 193 UN Member States accountable to the newly established SDGs. Over the years, it has evolved into a multidimensional analytical framework, as seen in the latest edition.

2.2 Annual Update Process and Collaborative Mechanisms (2016-2026)

Each annual update since 2016 has introduced methodological refinements. The early editions primarily focused on country rankings. However, later versions incorporated spillover indices and trend analyses. By the latest edition, comprehensive survey data from expert networks and the public have been included.

The collaborative mechanisms behind the annual updates involve a well-coordinated effort. SDSN’s secretariat collaborates with regional offices in Asia, Europe, and North America. An expanding network of local chairs and managers ensures the accuracy of data across all 193 countries.

2.3 Integration of Expert and Public Surveys in Report Refinement

The integration of expert and public surveys marks a significant methodological evolution. The latest edition includes the “2026 Expert Survey on Government Efforts for the SDGs,” covering 64 countries and the European Union. Additionally, it features the “2026 Survey on SDG Challenges and Means for Implementation,” which gathered insights from 1,098 respondents across 127 countries.

Annual decisions have been influenced by the shifting landscape of international development. For instance, the 2019 edition introduced the six SDG Transformations framework, while the 2020 edition addressed the impacts of the COVID-19 pandemic. The latest edition now pivots toward priorities beyond 2030 as the deadline approaches.

Initially affiliated with a university press, the report has matured into a globally recognized authority on SDG progress. Each edition builds on the previous year’s lessons, expanding the universe of data available for cross-country comparisons.

Importantly, all report materials—including the full PDF, Excel database with scores and ratings, codebook, and methodology documentation—are available for free. This commitment to democratizing data reflects the guiding principles that have shaped the report’s evolution since 2016.

3. Analysis of SDSN Expert and Large-Scale Surveys on SDG Implementation

The recent expert survey sheds light on the effectiveness of government initiatives related to the SDGs. It highlights how these efforts have been integrated into public management practices. This analysis draws on qualitative data collected from experts across various countries, providing a nuanced understanding of SDG implementation challenges.

3.1 The 2026 Expert Survey on Government Efforts

This year’s expert survey represents a methodological triumph in qualitative data collection. It mobilized 65 responses across 64 countries and the European Union. The survey assessed how deeply the SDG framework has penetrated national public management practices since 2018.

Countries like Canada, Denmark, Ghana, and Italy have made significant strides in incorporating the SDG framework into their governmental practices. In contrast, Australia, the United States, and Venezuela have not prioritized the SDGs in their public management frameworks.

3.2 Insights from the 2026 Large-Scale Survey on SDG Challenges

The large-scale survey, encompassing 1,098 respondents from 127 countries, provides a broader perspective on SDG outcomes. An overwhelming 78% of respondents believe that SDG outcomes in their countries have either improved or stagnated from 2015 to 2025.

However, the survey also identified significant barriers to SDG implementation. Notably, 89% of respondents pointed to the failure to implement approved strategies as a critical challenge. Additionally, 87% highlighted the shifting geopolitical landscape as another major hurdle.

3.3 Implications of Survey Findings on Policy and Implementation Practices

The findings from both surveys underscore the unique value of the SDSN in curating insights for the updated report. By triangulating expert assessments, public perceptions, and quantitative indicators, the network provides a multidimensional picture of government efforts.

This comprehensive approach informs the eight priorities for accelerating SDG progress through 2030 and beyond. It reveals that while bureaucratic structures remain in place, the political commitment at the highest levels is waning, as evidenced by the decline in heads of state referencing the SDGs in official speeches.

4. Role and Impact of Voluntary National and Local Reviews in Global SDG Monitoring

A modern conference room bustling with activity, showcasing a diverse group of professionals engaged in a dynamic discussion about Voluntary National and Local Reviews for Sustainable Development Goals (SDGs). In the foreground, a confident woman in business attire gestures toward a digital presentation displaying colorful charts and maps illustrating global progress. In the middle ground, colleagues (all in professional business attire) collaborate, surrounded by documents and laptops, creating a sense of teamwork and innovation. The background features large windows with a city skyline view, bathed in natural light, symbolizing transparency and hope. The mood is energetic and optimistic, reflecting the importance of collective efforts in global monitoring. The overall atmosphere is professional yet inspiring, encapsulated in a clean, contemporary design, embodying the essence of "The Sustainable Digest."

The mechanisms for Voluntary National and Local Reviews have emerged as pivotal tools in tracking global progress. Since 2016, 190 countries have participated in the Voluntary National Review (VNR) process. This achievement represents a remarkable feat of global accountability architecture, particularly in contrast to the three holdouts: Haiti, Myanmar, and the United States.

In 2026, 36 countries are scheduled to present updated reviews of their SDG action plans. Notably, there are no first-time presenters this year. Togo and Uruguay will present their fifth VNRs, showcasing their sustained engagement with this important mechanism. This evolution reflects how the VNR process has transformed from a one-off reporting exercise into an iterative policy learning cycle over the past decade.

The growth of Voluntary Local Reviews (VLRs) tells an equally compelling story. Subnational authorities in 48 countries have produced 386 VLRs from 2016 to 2026. Brazil, Malaysia, Mexico, and Argentina alone account for nearly half of these reviews. The number of VLR submissions surged by 69% from 62 in 2024 to 105 in 2025, indicating a robust local-level momentum for sustainable development.

4.5 Role and Impact of Voluntary National and Local Reviews in Global SDG Monitoring continuing..

UN DESA’s role as the institutional custodian of both VNRs and VLRs has expanded significantly. The Department maintains comprehensive databases tracking participation trends and provides technical support to governments preparing their reviews. This support ensures that these accountability mechanisms feed into the broader SDG implementation monitoring ecosystem.

The absence of the United States from the VNR process, alongside Haiti and Myanmar, highlights a significant gap in global SDG progress monitoring. This is particularly concerning given the country’s influence on international spillover effects, which the SDSN’s spillover index tracks across multiple indicators.

Ultimately, the VNR and VLR mechanisms embody the principle of country-led accountability that underpins the 2030 Agenda. UN DESA’s support infrastructure has evolved from basic reporting templates to sophisticated data platforms, enabling cross-country comparisons and peer learning among the 190 participating countries.

CountryVNR PresentationsVLR Count
Togo515
Uruguay510
Brazil472
Malaysia444
Mexico435
Argentina434
United States00

5. 2026 SDSN Sustainable Development Report Annual Update Review Analysis: Key Findings and Priorities

In this edition, we explore the vital discoveries and strategic priorities emerging from the latest global development evaluations. The 2026 findings reaffirm the Nordic dominance in sustainable development, with Finland, Sweden, and Denmark topping the rankings. However, the sdg index dashboards reveal a more complex narrative.

The spillover index illustrates how the consumption patterns of wealthier nations can negatively impact progress towards achieving the sustainable development goals in the Global South. This nuance is crucial for understanding the interconnectedness of global development efforts.

5.1 Overview of 2026 SDSN Report Rankings and Trends

The rankings from the development report 2026 indicate that while some countries excel, there are underlying issues that need addressing. The interactive maps within the report showcase the performance of nations on each of the 17 goals, providing a clear picture of where efforts are succeeding and where they are lacking.

5.2 Priority Areas and Emerging Issues in the Post-2030 Sustainable Development Agenda

The report identifies eight key priorities for accelerating sdg progress through 2030 and beyond. A remarkable consensus among experts reveals that at least 75% agree on six critical priorities for the post -2030 agenda. These include:

  • Strengthening means for implementation, focusing on governance and data.
  • Developing international guidelines on SDG synergies and trade-offs.
  • Incorporating artificial intelligence into future frameworks.
  • Reforming the global financial architecture to address budgeting gaps.
  • Ensuring stability in the framework while maintaining continuity in goals.
  • Better reflecting and incorporating international spillovers.

5.3 SDSN and UN DESA’s Collaborative Role in Shaping International Development Policies

The collaborative dynamic between SDSN and UN DESA plays a pivotal role in shaping international development policies. Their joint efforts highlight the importance of aligning government strategies with budget allocations. The findings indicate a persistent gap between adopting strategies and allocating necessary resources, which must be addressed in future negotiations.

Dr. Guillaume Lafortune’s recent publication emphasizes the need for a credible framework to guide the post -2030 agenda. This intellectual groundwork will help bridge the gap between academic rigor and practical policy applications, ensuring that future efforts are both informed and effective.

As we look toward 2030 and beyond, the sdg index dashboards serve not just as a report card but as a strategic compass. They provide actionable insights on where government efforts have succeeded and where they have stalled, guiding priorities for the future.

6. Conclusion

The synthesis of findings highlights the intricate tapestry of global initiatives at play. This edition showcases how the collaborative efforts of key organizations have matured over time. The convergence of expertise from various countries and institutions illustrates a commitment to advancing meaningful progress.

Moreover, the eight identified priorities serve as a roadmap for future actions. They not only address past shortcomings but also pave the way for innovative solutions. The free availability of data further exemplifies a dedication to transparency and accessibility.

As we navigate the path toward a more equitable future, the development process between these organizations stands as a model. It demonstrates how ongoing collaboration can yield actionable insights, ensuring that the global dialogue on sustainable development remains vibrant and impactful.

Key Takeaways

  • This report synthesizes ten years of data since the 2015 adoption of the 2030 Agenda.
  • It identifies eight priorities to enhance progress toward global goals.
  • Insights from expert and public surveys inform actionable strategies.
  • Top-ranking countries showcase effective long-term commitments.
  • Interactive tools allow for exploration of historical data trends.

Global Carbon: pricing, taxes, crediting, projects, footprint, REC, ESC, storage Explained

Global Carbon: pricing, taxes, crediting, projects, footprint, REC, ESC, storage

This Ultimate Guide frames how price signals, compliance schemes, voluntary credits, and renewables fit for U.S. decision-makers and international planners.

The landscape hit a record in 2022: revenues neared USD 100 billion and EU allowances reached €100. Yet most emissions still trade at modest levels; fewer than 5% face prices near the $50–$100/tCO2 range suggested for 2030.

Readers will get clear, practical steps on procurement choices—unbundled renewables, PPAs, and green tariffs—and guidance on integrity standards such as Core Carbon Principles and CORSIA. The piece contrasts direct instruments (tax and ETS) with hybrid standards and voluntary instruments that complement compliance systems.

Expect concise analysis of supply trends: renewables drove most credit issuance, nature-based registrations rose, and removals technology is growing under stricter quality screens. U.S.-specific notes touch on RGGI, SREC differences by state, and the federal solar ITC through 2032.

Carbon pricing at present: where markets, taxes, and credits stand now

Today’s price signals mix steady market gains with glaring coverage gaps that shape near-term decisions.

What a “price on carbon” means today for climate and energy decisions

A price on carbon is a monetary signal embedded in consumption and production choices; it nudges investment toward low-emitting assets and away from legacy polluters.

The tool works by raising the cost of emissions and making abatement economically visible. In 2022 revenues approached nearly USD 100 billion, while the EU ETS breached a symbolic €100 level — proof that robust signals can persist despite shocks.

Coverage versus price: why both matter for impact

Impact requires two levers: sufficient price levels to change marginal decisions, and broad coverage so a large share of emissions respond.

  • About 23% of global emissions were under ETS or levy systems by April 2023.
  • Fewer than 5% of ghg emissions faced direct prices in the $50–$100/tCO2 band, so many sectors remain exposed.

Markets and credits (compliance vs voluntary) both influence cost curves; only direct pricing enforces statutory abatement. Corporates should set internal price signals, align procurement, and rely on quality offsets to bridge near-term gaps. Solid data tracking is essential to forecast exposure and hedge procurement risks.

The pillars of pricing: carbon taxes, ETS, and hybrid systems

An intricately detailed, photorealistic image depicting the pillars of carbon pricing - a complex system of carbon taxes, emissions trading schemes (ETS), and hybrid systems. Showcase the inner workings of an ETS, with close-up views of emission allowances, trading platforms, and the intricate web of regulations. Capture the macro-level interactions between governments, industries, and the carbon market, set against a backdrop of modern cityscapes and industrial landscapes. Convey a sense of urgency and the high stakes involved, with muted tones and dramatic lighting. Prominently feature the brand "The Sustainable Digest" in the lower right corner.

The policy toolkit breaks into three practical choices: a per‑unit levy, a capped allowance market, and hybrids that mix benchmarks with trading. Each design shapes incentives and risk differently for firms and regulators.

Carbon tax fundamentals and current ranges in practice

A tax sets a transparent per‑ton price on emissions (or fuel). It is easy to administer and makes revenue predictable; governments can return funds as dividends or cut other levies.

Examples include Singapore’s planned rise to about USD 38–60 from 2026 and Canada’s pathway toward roughly USD 127 by 2030. Higher‑income jurisdictions often reach prices above $50 per tonne; middle‑income ones pilot lower levels while building measurement systems.

Emissions Trading Systems: caps, allowances, and trading

ETS create a cap on total emissions; regulators issue allowances (EUAs, UKAs, NZUs, KAU) that firms buy, sell, or bank. The cap delivers quantity certainty while markets reveal marginal abatement costs.

Hybrid models: OBPS, EPS, and regional cap-and-trade like RGGI

Hybrids try to shield trade‑exposed sectors. Output‑based performance standards (OBPS) and emissions performance standards (EPS) set benchmarks instead of pure per‑unit charges.

  • RGGI auctions allowances and directs proceeds to regional programs.
  • Hybrids reduce leakage but add design complexity and reliance on strong MRV for compliance.

Global price signals and coverage by region, based on World Bank 2023

Regional price bands reveal as much about institutional capacity as they do about political will. As of April 2023, 73 instruments covered roughly 23% of emissions worldwide. Yet less than 5% of ghg emissions faced a high‑level signal in the $50–$100/tCO2 range.

High-income versus middle-income bands

High‑income jurisdictions often cluster above $50 per ton; the european union’s ETS even hit €100, reinforcing strong market responses and revenue recycling.

Middle‑income systems mostly price under $10. Exceptions—Beijing and Guangdong pilots, Mexico’s subnational measures, and Latvia’s tax—show how pilots build MRV and administrative muscle.

Why coverage matters as much as price

A high signal on a sliver of emissions is not the same as modest signals applied broadly. A $75/t signal on 5% of emissions underperforms a $25/t signal covering half the economy when the goal is near‑term structural change.

  • Constraints: fossil fuel subsidies and energy volatility can blunt signals.
  • Capacity: MRV and admin readiness are gating factors for expansion.
  • Implication: closing the

Revenues from carbon pricing: record highs and how funds are used

Governments saw nearly USD 100 billion arrive from emissions-related instruments in 2022, shifting the budget conversation.

Most of that cash came from traded allowances rather than direct levies. About 69% of receipts were generated by ETS mechanisms, while roughly 31% came from tax-based schemes. The EU’s system alone produced about $42 billion in 2022 — nearly seven times its 2017 level — as auctioning replaced free allocation.

How countries recycle proceeds

Use of funds varies but trends are clear: roughly 46% of revenue is earmarked for targeted programs, 29% flows to general budgets, 10% serves as direct transfers (social cushioning), and 9% offsets other taxes.

Revenue SourceShare (2022)Main Uses
ETS (auctioning)69%Clean energy, innovation, adaptation
Tax-based levies31%Budget support, rebates, targeted transfers
EU auctioning$42BMarket tightening, transition aid, R&D

Policy implications

Predictable recycling improves public support and compliance. In the U.S., RGGI shows how reinvestment in efficiency and community programs builds durability.

Yet revenues remain price‑sensitive: allowance downturns or tax adjustments can cut fiscal inflows and weaken program credibility. Sound data tracking and transparent use of proceeds help stabilize expectations for investors and households alike.

Compliance markets around the world: EU ETS, China ETS, UK, K-ETS, NZ, Australia

A panoramic landscape showcasing the intricate workings of global carbon markets. In the foreground, a detailed illustration of the EU Emissions Trading System (EU ETS), with its trading platforms, registries, and compliance mechanisms. In the middle ground, smaller vignettes depict the China ETS, UK ETS, K-ETS, NZ ETS, and Australia's carbon pricing schemes. The background features a montage of renewable energy projects, carbon storage facilities, and sustainable technologies. The scene is bathed in warm, golden light, conveying the sense of progress and innovation in the world of climate finance. The brand "The Sustainable Digest" is subtly integrated into the artwork. Photorealistic rendering with a blend of macro and micro perspectives.

Compliance markets now form the backbone of many national climate strategies; each system creates unique signals for firms and regulators.

EU ETS and UK ETS: alignment, divergence, and EUA pricing dynamics

The european union’s ETS remains the largest by value and a global price benchmark. Its auction cadence and market design drive allowance liquidity and long-term expectations.

The UK launched an independent ETS in 2021. Designs share DNA, but governance differences have produced divergent EUA and UKA prices paths and trading patterns.

China’s power-sector ETS and expected sectoral expansion

China’s system started in 2021 and covers roughly 40% of national emissions through the power sector. Authorities plan phased expansion to steel, cement, and other heavy industries.

That expansion will reshape regional supply-demand dynamics and create larger cross-border hedging needs for firms exposed to Asian markets.

K-ETS, NZ ETS, and Australia’s ACCUs: coverage and policy evolution

South Korea’s K-ETS (2015) now covers about 75% of S1+S2 emissions and is in a liquidity-building phase.

New Zealand’s scheme covers more than half the national total; agricultural treatment remains an open policy frontier under review.

Australia relies on ACCUs as domestic offset-like units, with a cost-containment cap rising to AUD $75/tonne (CPI+2). These rules influence corporate hedging, procurement timing, and exposure across both allowances and offsets.

Voluntary carbon market and standardized contracts

A new set of futures—segmented by supply type and verification—lets buyers hedge quality risk ahead of delivery.

N-GEO: nature-based baskets

N-GEO packs verified AFOLU credits (Verra) into a tradable instrument. It aggregates forest and land‑use supply to smooth price swings and capture co‑benefits; buyers get bundled nature exposure with predictable forward quantities.

GEO: CORSIA-aligned aviation units

GEO mirrors ICAO CORSIA rules and draws from Verra, ACR, and CAR. That alignment tightens eligibility and raises baselines for aviation-grade integrity; it helps airlines meet offsets for international emissions while improving market trust.

C-GEO and Core Carbon Principles

C-GEO focuses on tech-based, non-AFOLU units that meet the Integrity Council’s CCPs. The CCPs set a quality floor—MRV rigor, permanence, governance—and narrow seller pools; the result is clearer pricing for high-integrity credits.

ContractSupply TypeKey Benefit
N-GEONature-based (Verra)Co-benefits; cheaper forward supply
GEOCORSIA-eligible (Verra/ACR/CAR)Aviation-grade acceptance; tighter eligibility
C-GEOTech removals (CCP-aligned)Higher integrity; lower permanence risk

Practical advice: blend N-GEO, GEO, and C-GEO to balance cost, quality, and forward certainty; use futures for trading and hedging. Note that some compliance regimes may recognize limited voluntary units under strict rules.

Projects and supply: renewable energy, nature-based solutions, and REDD+

A panoramic landscape showcasing an array of renewable energy projects, bathed in warm, golden hour lighting. In the foreground, a sprawling solar farm with sleek, reflective panels capturing the sun's rays. In the middle ground, towering wind turbines gracefully spinning, their blades cutting through the crisp air. In the distance, a gleaming hydroelectric dam nestled between lush, rolling hills. The scene is punctuated by pops of green foliage, hinting at the integration of nature-based solutions. The entire composition is captured with a cinematic, wide-angle lens, conveying a sense of scale and ambition. The Sustainable Digest brand name is subtly woven into the natural environment.

Patterns of supply now show dominant renewable energy output alongside a surging nature-based pipeline.

Renewable energy projects accounted for roughly 55% of issued units in 2022 and about 52% of retirements; wind and solar led issuance while falling technology costs reduced additionality concerns for large installations.

That decline in cost suggests issuance from new renewable energy schemes may taper as grid parity widens; buyers should expect shifting supply mixes over multi-year horizons.

Nature-based supply and REDD+

Nature-based solutions made up about 54% of new registrations in 2022, driven by biodiversity and livelihoods co-benefits; avoided deforestation (REDD+) and improved forest management remain core AFOLU sources.

  • REDD+ design focuses on avoided loss, leakage controls, and permanence buffers to manage long-term risk.
  • Latin America—Brazil, Colombia, Chile—updated forestry rules in 2023, expanding pipelines and governance.

Risks persist: baseline integrity, permanence, and social safeguards determine investability and unit performance over time.

Buyer advice: match geography and methodology to claimed outcomes (avoided emissions vs removals); prefer blended portfolios and multi-year contracts to hedge supply and quality risk.

Renewable Energy Credits (RECs) and SRECs: how they work and how to buy

Renewable energy certificates certify one megawatt-hour of clean generation; they capture the attribute of green power, not the physical electron. Think of a serial-numbered proof of production.

The issuance process includes a unique registry serial, a generation timestamp, and a formal retirement step to prevent double counting. These tracked credits let buyers claim renewable energy use while grids mix electrons.

Procurement pathways

  • Unbundled certificates deliver speed and flexibility; they are lowest-friction for offsetting consumption.
  • PPAs provide additionality and long-term price certainty for a larger renewable energy project.
  • Utility green tariffs and green pricing are simple on-ramps for organizations that prefer a managed offering.
  • On-site self-generation produces SRECs or surplus certificates that can offset local loads or be sold into the market.

Prices and policy basics

SRECs—solar-specific certificates—vary widely by state, often ranging from about $10 to $400; some wind certificates trade as low as $1–$8. The U.S. federal solar investment tax credit (ITC) is 30% for systems installed through 2032, which affects payback and overall cost.

Practical buyer advice

Match vintage and geography to program rules and distribute purchases across sites for proportional coverage. For compliance users, ensure certificate attributes meet local requirements and that retirement is verifiable to avoid claims that conflict with emissions accounting.

RECs vs carbon credits: different instruments, different impacts

Detailed photorealistic image of a diverse range of renewable energy sources, including wind turbines, solar panels, hydroelectric dams, geothermal plants, and biofuel production facilities. The scene showcases the interconnected nature of these technologies, with clean energy infrastructure seamlessly integrated into natural landscapes. Vibrant colors, sharp focus, and dramatic lighting create a sense of power and progress. In the foreground, a central display prominently features the logo "The Sustainable Digest", highlighting the publication's focus on renewable energy and sustainability. The overall composition conveys the message of a sustainable future powered by clean, renewable sources.

RECs and carbon credits play distinct roles in corporate climate strategy. One documents renewable electricity attributes in kWh; the other represents a tonne of avoided or removed CO2e.

Offsetting electricity (kWh) versus GHG mitigation (tCO2e)

Market-based Scope 2 accounting recognizes renewable energy certificates for electricity use. That helps firms claim green energy consumption without changing grid flows.

By contrast, a carbon credit quantifies a reduction or removal of carbon emissions. Those units address Scope 1 or Scope 3 exposures where allowed.

  • Clarity: RECs = attribute per kWh; carbon credits = tonne-level mitigation.
  • Accounting: use market-based certificates for electricity; apply high-quality offsets for residual emissions.
  • Integrity: disclose boundaries, vintage, and methodology to avoid double claims.

Combine efficiency, on-site renewable energy, and then select verified credits for remaining emissions. Over-reliance on unbundled certificates can look cosmetic and risk reputation. A balanced portfolio gives both energy claims and real emissions results.

ESC and performance-based approaches: EPS, OBPS, and sector benchmarks

Where full economy-wide charges stall, performance approaches offer a pragmatic path for hard-to-abate industries. Canada’s OBPS taxes emissions above output-based benchmarks; the UK operates an EPS model; several U.S. states use similar standards.

How they work: intensity targets tie allowable pollution to production output. Facilities that beat the benchmark can earn tradable compliance units; those that lag must pay or purchase units to meet obligations.

Policy position: hybrids fill gaps where full caps or levies face political or administrative hurdles; they also reduce leakage risk for trade-exposed firms. Benchmarks often sit alongside an ets or free allocation, shaping who gets credits and who pays.

  • Design note: benchmarks reward intensity improvements rather than absolute cuts.
  • Market interaction: over-performance creates supply of compliance units that trade in secondary markets.
  • Industry advice: audit baselines, plan capital upgrades, and register performance early to monetize gains where allowed.

For companies, the practical step is simple: measure ghg and output carefully, test upgrades against benchmarks, and treat these systems as another compliance channel in carbon risk planning.

Carbon storage and removals in markets: from nature to tech

A breathtaking landscape showcasing the future of carbon storage and removal technologies. In the foreground, a towering carbon capture facility stands proud, its sleek design and efficient operation a testament to human ingenuity. The midground reveals lush, verdant forests, nature's own carbon sinks, with intricate leaf structures and vibrant hues. In the distance, rugged mountains rise, their rocky peaks capped with pristine snow, a symbol of the delicate balance between technology and the natural world. Lighting is soft and directional, casting gentle shadows and highlighting the textures of the scene. The overall mood is one of hopeful optimism, a vision of a sustainable future where "The Sustainable Digest" chronicles the progress of carbon management.

Not all removals are created equal; the market is learning to pay a premium for permanence. Nature-based options (afforestation, reforestation, improved forest management) supply broad volumes, while engineered solutions (DACCS, mineralization) deliver durability at higher cost.

Nature-based versus tech-based crediting

Removals remove CO2 from the atmosphere; avoided emissions prevent further releases. Markets now price that difference—true removals command higher rates because they reduce legacy concentration.

Permanence and risk differ sharply. Tech-based removals tend to offer stronger durability; nature-based supply needs buffers, monitoring, and active stewardship to manage reversal risk.

  • Cost profile: tech = premium; nature = larger supply but integrity scrutiny.
  • Procurement tip: match a carbon offset type to your claim—removal vs reduction—and budget limits.
  • Standards matter: CCPs and CORSIA-style rules push clearer disclosure and better MRV.

Buyers should blend units: use nature for volume and tech removals to meet permanence needs and reputation goals.

Measuring your carbon footprint and using credits/RECs credibly

A modern, well-lit office space, with large windows letting in natural light. In the foreground, a desk with a laptop, calculator, and various carbon measurement tools - emissions calculators, energy usage monitors, and carbon accounting software. The mid-ground features a team collaborating, discussing data and analyzing charts on the screen. In the background, a wall-mounted display shows a detailed carbon footprint analysis, with different sectors and emissions sources highlighted. The overall mood is focused, professional, and data-driven. "The Sustainable Digest" logo is subtly incorporated into the scene.

Accurate measurement and clear rules turn good intentions into credible climate claims. Start by defining boundaries for Scope 1, Scope 2 (location vs market-based), and Scope 3 so inventories reflect actual operational exposure.

Scopes, market-based accounting, and avoiding double counting

Market-based Scope 2 accounting recognizes renewable certificates; standardized registries use serial numbers and retirements to prevent duplicate claims. Voluntary retirement reached roughly 196 million units in 2022, showing market maturation.

Document contracts, attestations, and registry retirements clearly; auditors expect traceable records. This practice reduces reputational risk and improves compliance readiness.

Integrating efficiency, renewables, and high-quality offsets

Follow a hierarchy: improve efficiency first, then buy renewables through PPAs or on-site systems (the U.S. solar ITC offers a 30% incentive through 2032), and use high-quality credits only for truly residual emissions.

Practical tip: set an internal carbon price to steer capital and align procurement with expected external signals. Transparent reporting, registry exclusivity, and strong data governance keep claims defensible.

Global Carbon: pricing, taxes, crediting, projects, footprint, REC, ESC, storage

A striking photograph showcasing the diverse forms and textures of carbon in its natural and industrial states. The image features a central close-up of a graphite pencil tip, revealing the intricate, layered structure of this allotrope. Surrounding it, a series of macro and micro shots depict the raw mineral form of graphite, the amorphous structure of activated charcoal, and the geometric patterns of carbon nanotubes. Woven throughout, subtle hints of "The Sustainable Digest" branding create a cohesive, visually compelling narrative about the global carbon cycle. Dramatic lighting and a muted color palette evoke the seriousness and importance of the subject matter.

This section ties price signals, coverage regimes, and procurement tools into a compact playbook for decision-makers. It links major program examples—EU ETS at the €100 milestone, the UK ETS after Brexit, China’s power-sector ETS (~40% coverage), K-ETS (~75% of S1+S2), New Zealand’s economy-wide scheme, and Australia’s ACCUs cap (AUD 75, CPI+2)—to practical buying choices.

Key connections to remember:

  • Compliance and voluntary domains interact; standards like CORSIA and CCPs raise the quality floor for credits.
  • Procurement playbook: unbundled certificates, SRECs/on-site solar, long-term PPAs, green tariffs, and verified offsets or removals.
  • VCM instruments (N-GEO, GEO, C-GEO) provide nature, aviation, and tech pathways for forward coverage.

Practical note: U.S. buyers should watch EU, UK, and China price signals as strategic indicators. A blended approach—using renewables for immediate claims and high-integrity credits for residual co2—keeps plans defensible and aligned with evolving market dynamics.

What U.S. buyers should know now: RGGI pathways, PPAs, and procurement strategy

Expansive aerial view of a diverse renewable energy landscape, featuring gleaming wind turbines, sprawling solar farms, and hydroelectric dams nestled in lush, verdant surroundings. Intricate close-ups showcase the inner workings of these cutting-edge technologies, from the intricate solar panel arrays to the towering wind turbine blades. A sense of clean, efficient power emanates throughout, complemented by a vibrant, optimistic atmosphere. The overall scene conveys a vision of a sustainable future, one where "The Sustainable Digest" celebrates humanity's progress towards a greener, more environmentally conscious world.

For U.S. procurement teams, the key decision is balancing speed, certainty, and reputation when buying renewable energy and complementary credits. This choice affects exposure to allowance costs, wholesale prices, and compliance risk.

Choosing between unbundled certificates, on-site solar, and long-term PPAs

Unbundled certificates are fast and flexible; they suit near-term claims and short windows (21 months for some programs). On-site solar gives operational value and pairs with the 30% federal solar tax credit through 2032.

Long-term PPAs (10–20 years) add additionality and hedge against volatile wholesale prices; they also help finance large energy projects.

OptionSpeedAdditionality / HedgeTypical Tenor
Unbundled certificatesFastLow additionalityShort (0–3 yrs)
On-site solarMediumOperational value; ITC benefitAsset life (20+ yrs)
Long-term PPASlowHigh; price hedge10–20 yrs

Applying CORSIA-grade and nature-based credits in U.S. portfolios

Use GEO (CORSIA-grade) and N-GEO/C-GEO blends to cover residual emissions. Carbon credits that meet CCP standards improve quality signals and reduce reputational risk.

Note RGGI auctions can push allowance costs into retail rates; buyers should model that exposure and consider incentive programs, SREC variability by state, and PPA tenor when planning trade-offs.

Outlook to 2030: scaling prices, coverage, and integrity

An expansive vista of a bustling financial district, towering skyscrapers reaching toward the sky. In the foreground, a close-up of a digital display, showcasing fluctuating carbon prices against a backdrop of cascading numbers and charts. The scene is bathed in warm, golden light, creating a sense of urgency and anticipation. Subtle reflections dance across the sleek, glass facades, hinting at the complex interplay of global markets. The Sustainable Digest logo is discretely embedded within the scene, a testament to the publication's expertise in this domain. A striking balance of micro and macro perspectives, conveying the scale and significance of carbon pricing in the evolving landscape of sustainability.

Expect stronger financial nudges over the next decade as regulators tighten limits and extend coverage into new sectors.

World Bank scenarios point to a $50–$100/tCO2 band by 2030 to align with temperature goals. Today, fewer than 5% of global emissions face that signal; roughly 73 instruments cover about 23% of emissions.

That gap means policy design will determine whether prices actually climb or merely ping regional markets. Key levers include tighter caps, reduced free allocation, escalator fees, and sector expansion into heavy industry and transport.

Implications for markets and supply

Expect three shifts: wider systems coverage, higher per‑ton values, and stronger integrity rules. The EU ETS milestones show how rapid tightening can lift market signals.

  • Coverage: more jurisdictions will add or link trading systems and hybrid benchmarks.
  • Integrity: CCPs and CORSIA-style norms will raise baselines, permanence, and transparency.
  • Supply: AFOLU pipelines will mature while tech removals win a price premium for durability.

For U.S. buyers the practical steps are clear: set an internal price, lock long-term PPAs where possible, and pre-position for higher-quality offset supply to manage exposure and reputational risk.

Conclusion

Total conclusion of carbon and climate context

Policy signals, rising receipts, and stronger standards have nudged the market toward maturity; 2022 revenues neared USD 100 billion while voluntary retirements reached roughly 196 million units.

Coverage remains uneven: about 73 instruments now touch ~23% of global emissions, and fewer than 5% of emissions face the $50–$100 per‑ton band. Nature-based registrations supplied roughly 54% of new supply in recent years.

The practical playbook is unchanged: cut energy use first; deploy renewables and long-term contracts; then buy high-quality credits for residual emissions. Internal pricing, clear governance, and transparent claims will matter as signals tighten.

Integrity and scale must advance together; only that tandem will deliver durable change across the world in the coming years.

Key Takeaways

  • 2022 revenues reached record levels while price exposure remains uneven across regions.
  • Direct pricing (tax/ETS), performance standards, and voluntary credits play different roles.
  • Renewable credits dominate supply; nature-based and tech removals are expanding.
  • U.S. options include RGGI pathways, SREC variability, and the 30% solar ITC.
  • Only a small share of emissions face near-$50–$100 prices today; scale and integrity are urgent for 2030.

This website is saving the energy of your screen as it is not being used. It's part of a global effort to lower the planet's electrical consumption and CO2 emission level. Resume browsing
Click anywhere to resume browsing
Verified by MonsterInsights